

Quicken: Intelligent Money
by Quicken Inc.
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
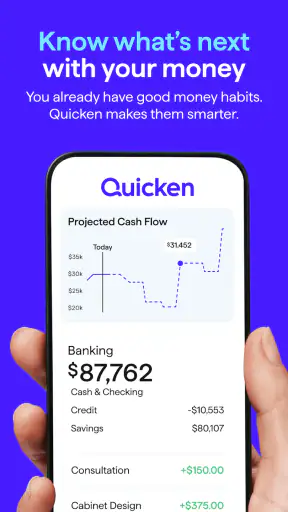
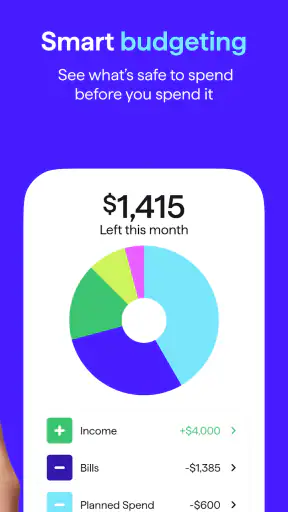
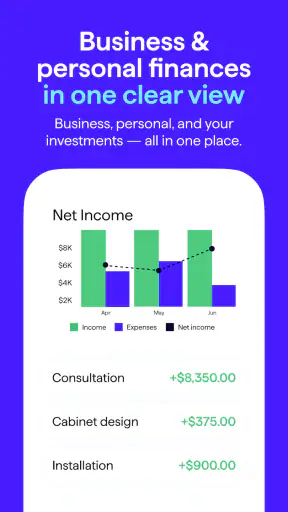
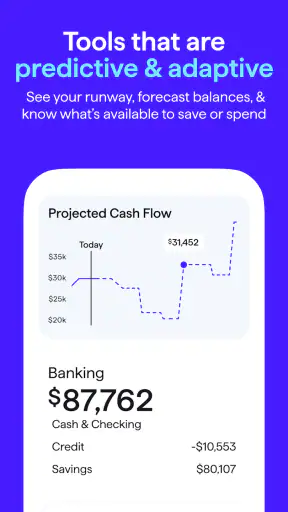
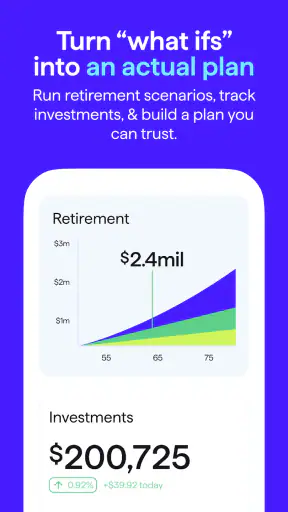
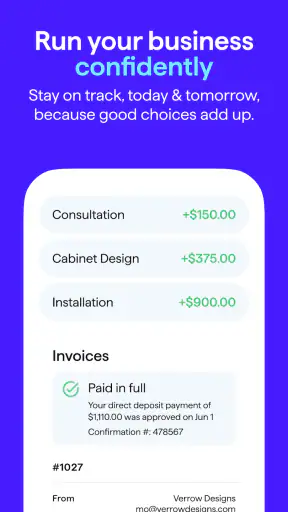
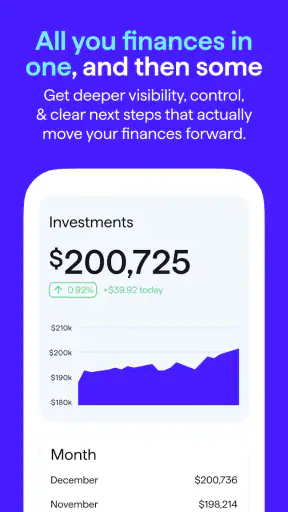
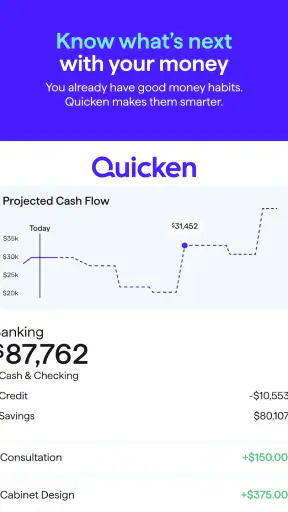
 Analysis by Getfullapps
Managing money on a shared household device sounds simple until everyone needs a different view of the same financial life. One person may be watching monthly spending, another may be checking a side business, and both may want useful information without mixing every detail together. I found Quicken: Intelligent Money most interesting in that situation because it brings budgeting and personal finance into one place while also including tools aimed at small business use.
I approached it less like a quick expense notebook and more like a central dashboard for people who want to understand where their money is going. That distinction matters. It can be helpful when a household is ready to review patterns, plan ahead, and coordinate decisions. It is less appealing if all you want is a two-minute way to record a coffee or split a restaurant bill.
The app is free to install, is listed for Everyone, and comes from Quicken Inc. Its average rating is 4.7 from around 4.9K ratings, with over 500K installs. Those figures suggest that it has found an audience among people looking for a more substantial financial tool rather than a novelty calculator. In my experience, its value depends heavily on how carefully you define who is using it, what information belongs together, and what should remain separate.
How Quicken works in a shared household
When I think about using a finance app across a household, the first question is not who gets to see every transaction but what decisions the shared view should help everyone make. I’d agree on a limited purpose—such as reviewing common costs—then keep personal and work-related money distinct where that makes the picture clearer. That gives the routine a useful boundary and makes it easier to decide what to review together next.
A realistic home-money routine
Imagine a couple using a tablet in the kitchen at the end of the week. One person reviews the household budget, checks recurring bills, and looks for categories that are drifting upward. The other uses the same device to think through income and expenses from a small freelance activity. Having one finance app available can make the conversation easier because both people are looking at organized information instead of trying to reconcile notes, spreadsheets, and banking screens.
That is where I see the strongest household use case. The app can act as a place for financial review, not merely a place to enter transactions. A weekly check-in might cover upcoming obligations, recent spending, and whether the current plan still matches reality. This approach is more useful than opening the app only when something goes wrong.
There is also a practical trade-off. A shared device makes access convenient, but convenience can blur personal boundaries. If several people use the same phone or tablet, I would decide in advance whether the app is for joint household finances, one person’s private finances, or a clearly defined combination. The software should not be treated as a substitute for an agreement about privacy.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Why the small-business angle changes the picture
The inclusion of small-business tools makes the app more relevant to households with mixed financial responsibilities. Someone who earns occasional income outside a regular job may want to think about personal spending and work-related money in the same overall planning routine. That can reduce the need to jump between a household budget and a separate business notebook.
Still, I would not automatically merge every account or expense simply because the app can support both kinds of activity. Separating household costs from business costs is important for clear decision-making. A useful workflow is to review the household picture first, then examine business-related activity on its own terms. That keeps a strong month in one area from hiding a problem in the other.
This is one of the less obvious strengths of Quicken: Intelligent Money. Its usefulness is not limited to families with identical financial goals. It can support a household in which one person has ordinary personal budgeting needs and another has a modest independent income stream. The benefit comes from disciplined organization, not from assuming that all money should be viewed as one pool.
Setting boundaries before entering information
My first recommendation is to decide what the app is supposed to answer. Is the main question, “Can we afford this month?” Is it, “Where are we overspending?” Or is it, “How should personal and small-business money be reviewed without confusion?” A clear purpose makes the setup easier to judge and prevents the app from becoming a crowded record of everything.
On a shared device, I would also agree on who is responsible for maintaining the information. If one person categorizes transactions while another only checks summaries, both people should know that the view depends on the first person’s consistency. If everyone edits or reviews without a routine, disagreements may be mistaken for app problems when they are really process problems.
The most important household setup decision is deciding what belongs together before trying to track it together. That simple rule helps avoid a common mistake: combining personal, shared, and business activity so thoroughly that the resulting picture becomes difficult to interpret.
Coordination without turning money into a daily argument
A finance app can improve coordination, but it cannot settle disagreements about priorities. I would use it to prepare a conversation, not to win one. For example, a household could review broad spending categories together and then decide which changes are realistic. The app provides structure; the people still need to agree on what matters.
One useful habit is to schedule a short review rather than checking constantly. A weekly or twice-monthly conversation gives enough time for patterns to appear without making every purchase feel like an audit. It also creates a natural moment to correct a category or clarify whether an expense was personal, shared, or connected to work.
Another helpful distinction is between visibility and control. Seeing household information can support cooperation, but it does not mean every person should have the same role in maintaining it. I would keep the process transparent while still respecting that adults may have individual financial commitments. Quicken: Intelligent Money works best when the household agrees on the level of shared visibility instead of assuming that one arrangement suits everyone.
What the app is like compared with simpler alternatives
Compared with a basic notes app or spreadsheet, this is a more purpose-built choice for people who want an ongoing view of budgets and personal finances. A spreadsheet can be extremely flexible, but it also requires you to design the categories, formulas, and review process yourself. Quicken gives the task a more focused home, which is valuable when the goal is regular financial organization rather than building a custom system.
Compared with a lightweight expense tracker, it may feel heavier. A simple tracker is often better for someone who only wants to record purchases quickly and see a basic total. The broader budgeting and small-business orientation here makes more sense when you want to examine financial activity over time and coordinate decisions with a partner or household.
It also differs from using only a bank’s mobile app. A banking app is naturally useful for checking balances and recent transactions, but it is usually centered on that institution’s accounts. A dedicated finance tool can be more useful for thinking across the household picture. The trade-off is that broader organization requires more attention from the user and may take longer to feel comfortable.
Trust, age, and shared access
The Everyone age classification makes the app broadly approachable from an age-rating perspective, but that should not be confused with financial readiness. I would be comfortable introducing the ideas of budgeting and categories to a younger household member under adult guidance, yet I would not hand over sensitive financial responsibility simply because an app is easy to install.
For teenagers or inexperienced users, the best role may be observation and discussion. They can learn why a household separates needs from optional spending, how recurring obligations affect available money, and why business income should not automatically be treated as spending money. The app can support those conversations, but an adult should decide what information is appropriate to share.
Trust matters just as much between adults. On a shared device, I would avoid leaving the app open when other people can casually browse it. I would also agree on whether the device is a convenient access point or the household’s only access point. If one person travels, changes devices, or needs privacy, relying entirely on a shared screen can become inconvenient.
This is not an argument against household use. It is a reminder that financial software exposes context as well as numbers. Even a category total can reveal personal habits, work arrangements, or private commitments. A good shared setup recognizes that coordination and personal boundaries can exist at the same time.
Practical workflows that make it more useful
The first workflow I recommend is a “household first, business second” review. Begin with the money needed for ordinary shared obligations, then move to the small-business side. This prevents irregular work income from making the household budget look healthier than it really is. It also makes it easier to discuss whether business costs should be planned separately.
The second is a category-cleanup session. Instead of waiting until the budget feels wrong, review unclear or inconsistent entries at a regular interval. The goal is not perfect labeling for its own sake. The goal is to make future decisions based on comparable information. A category that changes meaning from week to week can produce a misleading impression even when every transaction is present.
The third is to use the app as a decision checkpoint before a major household commitment. Rather than asking only whether the current balance can cover something, look at the wider budget and upcoming obligations. This is a more mature use of a finance app than checking whether there is enough money today. It turns the tool into part of a planning conversation.
A fourth insight is to keep responsibility visible. If one person maintains the records, the other should know when the information was last reviewed and what assumptions are being used. That does not require constant supervision. It simply prevents the household from treating an outdated view as a shared fact.
Where friction may appear
The biggest limitation is that a broad financial tool asks more from the user than a minimal tracker. You need to think about structure, categories, boundaries, and review habits. Someone who dislikes financial organization may stop using it before the benefits become clear. In that case, a simpler app or a small shared spreadsheet could be the better choice.
There is also a learning curve created by the combination of personal and small-business tools. That combination is useful for the right household, but unnecessary for someone with a single uncomplicated budget. Extra scope can make an app feel less direct, especially when the user wants one quick answer rather than a complete financial overview.
The free price is appealing for trying the app, but in-app purchases range from $9.99 to $109.99 per item. I would therefore examine which parts of the experience matter to my household before committing to paid options. The important question is not simply whether the app can be installed without payment, but whether the ongoing value matches the way the household intends to use it.
I would also skip it if my main requirement were a dedicated bill-splitting tool, a very private personal ledger, or an ultra-fast way to record occasional expenses. Its strengths are planning, organization, and a wider view. Those strengths can feel like unnecessary weight when the financial task is narrow.
Who should use it and who should look elsewhere
I think Quicken: Intelligent Money is a good fit for a household that wants a recurring budget conversation, has enough financial activity to justify organization, or combines personal money management with small-business needs. It is especially suitable when two adults can agree on categories, responsibilities, and the amount of information they want to share.
It is less suitable for someone who wants an app to make financial decisions automatically. The user still has to interpret the information and act on it. It is also not my first recommendation for a person who wants complete separation between household finances and a small business, unless they are willing to maintain that separation carefully within their own workflow.
For a single user with simple finances, a bank app or lightweight tracker may be quicker. For a household with several moving parts, a spreadsheet may become difficult to maintain. This app sits between those extremes: more structured than a blank sheet, but more demanding than a basic spending log.
My household verdict
After looking at it through the lens of shared-device use, I see Quicken: Intelligent Money as a practical finance workspace rather than a casual expense utility. Its combination of budgeting, personal finance organization, and small-business tools gives it a clear purpose for households whose money does not fit into one simple category.
I would recommend starting with a narrow plan: define the shared purpose, decide which information stays personal, and establish one regular review routine. That approach makes the app easier to understand and reduces the chance that shared access becomes uncomfortable. It also gives each person a fair chance to see how the system works before adding more complexity.
The app is free to begin with, carries an Everyone age rating, and has been developed by Quicken Inc. Since paid items range from $9.99 to $109.99, I would treat the initial period as a test of household fit rather than assuming every available tool is necessary. If the app helps your household make calmer, clearer decisions, its broader design is justified. If you only need quick personal entries, its scope may be more than you need.
My final view is positive but conditional: choose it when your household needs a shared financial picture with clear boundaries, not merely a place to jot down purchases. Used with agreed responsibilities and sensible privacy habits, it can turn scattered money conversations into a repeatable routine. Used without those boundaries, even a well-organized finance app can make household coordination harder instead of easier.
Pros
- Clear spending categories make it easier to understand where your money goes.
- Useful budgeting tools help track progress toward monthly spending limits.
- Bill reminders can reduce the risk of missing recurring payments.
- Investment tracking provides a broader view of your financial position.
- Syncing across devices keeps financial information available when you need it.
Cons
- Many useful features require a paid subscription.
- Account connections may occasionally need to be refreshed or reauthorized.
- The interface can feel overwhelming for users managing complex finances.
- Some features depend on support from your bank or financial institution.
- Manual corrections may be needed when transactions are categorized incorrectly.
FAQs for Quicken: Intelligent Money
What is Quicken: Intelligent Money, and who is it designed for?
Quicken: Intelligent Money is a personal finance app designed to help users organize accounts, monitor spending, track budgets, manage bills, and understand their overall financial position. It is most useful for people who want a broader view of their money across multiple institutions rather than relying on separate banking apps. Before downloading, check whether its features and subscription options match your financial goals and preferred level of account management.
Can Quicken: Intelligent Money connect to my bank and credit card accounts?
The app is intended to bring financial information from supported banks, credit cards, investment accounts, and other institutions into one place. However, connection availability can vary by institution, account type, region, and the synchronization service being used. You may occasionally need to reauthenticate an account or resolve a connection error. It is worth confirming that your financial institutions are supported before depending on the app for complete, up-to-date information.
Does Quicken: Intelligent Money cost money to use?
Quicken: Intelligent Money may require a paid subscription for access to its full set of financial management tools, while the exact price and available plans can depend on the platform, region, and current promotion. Some features may be limited without an active membership. Review the subscription details carefully before starting a trial, including renewal terms, billing frequency, cancellation rules, and whether the plan covers the devices and services you intend to use.
Is Quicken: Intelligent Money safe for managing personal financial information?
Because the app handles sensitive financial information, security should be an important consideration before use. Quicken generally relies on account-protection measures such as encrypted data transmission, secure sign-in procedures, and authentication options, but no online service can eliminate every risk. Use a strong, unique password, enable available security features, keep your device updated, and avoid accessing financial data over unsecured public networks whenever possible.
What can I do if my account data is missing or does not update correctly?
Account synchronization is convenient, but updates can sometimes be delayed or interrupted by bank maintenance, changed login credentials, security requirements, or temporary connection problems. If information appears incomplete, first refresh the account and verify that the institution has not requested new authorization. You should also review the transaction date and connection status. For unresolved issues, consult Quicken support rather than assuming the displayed balance is fully current.

Quicken: Intelligent Money
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mobilefeedback@quicken.com, visit https://www.quicken.com/products/simplifi/, or review their http://www.quicken.com/privacy.










